Financial Mistakes to Avoid: Safeguard Your Future
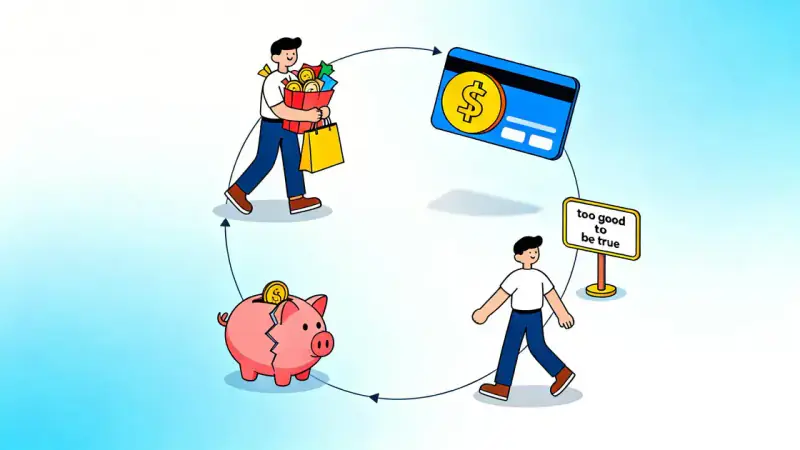
Financial mistakes to avoid can change your financial landscape. Recognizing these errors is crucial for your economic well-being. Many individuals fall prey to overspending and poor planning.
By understanding common pitfalls, you can make better financial choices. This article aims to highlight key areas where mistakes often occur.
Keep reading to discover how you can avoid these missteps and secure your financial future.
Understanding Financial Mistakes
Understanding financial mistakes is crucial for both short-term stability and long-term success. Learning about Financial Mistakes to Avoid helps individuals recognize how everyday decisions can impact their finances.
Common mistakes might include overspending or neglecting to save. Being aware of Financial Mistakes to Avoid allows you to see how each choice affects your broader financial picture.
Identifying these pitfalls early can help you steer clear of future issues. Knowing the Financial Mistakes to Avoid builds a strong foundation for healthy and sustainable financial habits.
Common Financial Pitfalls
Common financial pitfalls can hinder your path to success. Identifying these mistakes helps you navigate your finances better. Many people fall into traps that lead to stress and debt.
Some typical mistakes include overspending, not saving for emergencies, and failing to plan for retirement. These can have long-term effects on your financial health.
Being aware of these pitfalls allows you to make informed choices. Smart financial decisions are vital for a brighter financial future.
How to Create a Budget
- Calculate your income: list all sources of money you receive each month.
- Track your expenses: write down fixed and variable costs to see where your money goes.
- Set financial goals: define short- and long-term objectives to guide your spending.
- Create spending categories: organize expenses into clear groups with limits.
- Review and adjust regularly: update your budget to reflect changes in income or expenses.
The Importance of Saving
The importance of saving cannot be overstated. Saving money helps you prepare for emergencies and future goals. Having savings gives you peace of mind when unexpected expenses arise.
Savings can provide security during tough times, like losing a job or facing medical bills. It also helps you reach bigger goals, such as buying a home or starting a business.
Smart saving habits can create a stronger financial future. By saving regularly, you invest in your own well-being.
Investing Mistakes to Avoid
Investing mistakes to avoid can cost you money and time. Many novice investors make common errors that lead to poor choices. Recognizing these pitfalls is a critical step toward better investment decisions.
One mistake is not doing enough research. Understanding the companies or assets you invest in helps minimize risks. Another error is letting emotions decide your moves.
Staying calm during market ups and downs is essential. Always have a clear strategy to follow to avoid these common mistakes.
Debt Management Strategies
Debt management strategies are crucial for regaining financial control. When debts pile up, they can cause stress and limit your options. Knowing how to manage them effectively can lighten the burden.
One effective strategy is creating a payment plan. Set a budget that prioritizes debt repayment. This makes it easier to track your progress.
Another method is to consider consolidating your debts. This means combining multiple debts into a single loan, which can lower your interest rate and simplify payments.
Planning for Retirement
Planning for retirement is essential for a secure future. It’s never too early to start saving. The earlier you save, the more time your money has to grow.
Set clear goals about how much money you’ll need. Understand your lifestyle choices and expenses during retirement. This helps guide your saving strategy.
Consider various retirement accounts, like 401(k)s or IRAs. Each has different benefits and rules that can support your retirement plan.
Smart Spending Habits
Smart spending habits are essential for managing your finances. When you practice smart spending, you make informed choices about where your money goes. This helps you avoid unnecessary expenses.
Start by tracking your spending. Knowing where your money is spent can help identify areas to cut back. This awareness leads to better budgeting.
Buying only what you need, seeking discounts, and comparing prices are all effective habits. These choices not only save money but also keep you within your budget.
Emergency Fund Essentials
Emergency fund essentials are critical for financial security. An emergency fund is money set aside for unexpected expenses. This could be medical bills, car repairs, or job loss.
It’s recommended to save three to six months’ worth of living expenses. Having this buffer helps avoid debt when emergencies arise.
Build your fund gradually by saving a set amount each month. Even small contributions add up over time, giving you peace of mind during tough situations.